Case Study: How My First-Time Buyer Got a $476,000 Poolesville Home for About $3,200 Out of Pocket
$24,000 off the list price, $14,000 in seller-paid closing costs, $50,000 in Maryland Mortgage Program help, and a $2,377 check back at closing. The full numbers from a July 2026 Poolesville purchase.
Edward Dumitrache
October 27, 2026
Part of: The Complete Guide to Buying a Home in Montgomery County, MD · See all client results
The short version: in July 2026 my client Ovi C., a first-time buyer, bought a 4-bedroom split level at 17313 Dowden Way in Poolesville for $476,000. That's $24,000 below the list price. The seller also paid $14,000 of his closing costs. The Maryland Mortgage Program covered his entire down payment. At the settlement table he got $2,376.85 back.
His total cash to get the keys: about $3,200, including the appraisal. And before he made the offer, I ran the comparable sales for him: about $596,000 after a light refresh, about $615,000 fully renovated. He knew the upside before he signed anything.
No commission rebate was involved. This came from running the numbers, negotiation, a state program most buyers don't know about, and knowing when a seller needs to sell.
Every number below comes from the final settlement statement and the Bright MLS record.
The house nobody else wanted
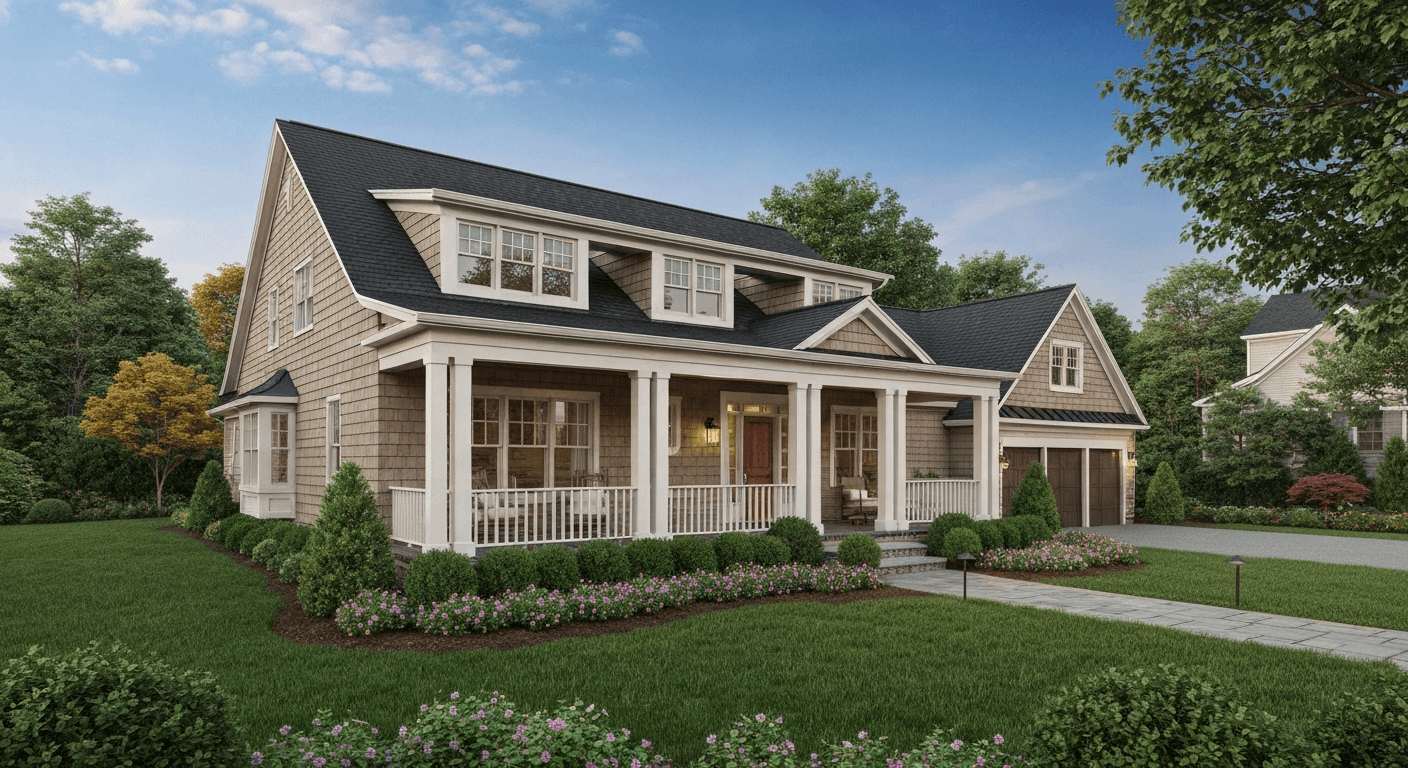
17313 Dowden Way is a 1974 split level in the Wesmond neighborhood of Poolesville: 4 bedrooms, 2.5 baths, 1,440 finished square feet above grade, a basement, an attached garage, a fenced yard and a pool. It sits in the Poolesville school cluster, one of the reasons buyers look in the Town of Poolesville in the first place.
It went on the market on June 16, 2026 at $535,000, sold as-is. Within days the price dropped to $500,000.
When we walked it, I could see why. It wasn't in the condition buyers expect at that price, and other buyers weren't biting. That combination, a fast $35,000 price cut, an as-is sale, and a house that needed work in a town where good homes sell quickly, tells me one thing: this seller needs to sell.
There's an old line I like, with a little Dracula in it: when I see blood, I go for the jugular. Not to hurt the seller, but because my job is to get my client the best possible deal, and a motivated seller is exactly when that's possible.
I ran the comps for my buyer before we made an offer
Before Ovi decided anything, I pulled the comparable sales to answer two questions for him: what is this house worth today, and what will it be worth once it's fixed up? Three split levels with basements, built 1973–75 in Poolesville:
| Comparable sale | Sold | Size | Notes |
|---|---|---|---|
| 19916 Westerly Ave | $700,000 (May 13, 2026) | 1,366 sq ft, 4 bd / 2.5 ba | Renovated and staged, 3 days on market |
| 19821 Spurrier Ave | $615,000 (Apr 2, 2026) | 1,563 sq ft, 3 bd / 2.5 ba | Cash sale, 9 days on market |
| 17528 Collier Cir | $550,000 (Dec 2, 2025) | 1,520 sq ft, 4 bd / 2.5 ba | 104 days on market |
Homes in the area were selling in a median of 9 days at about 99% of list price. Here's what the comps told us, laid out for Ovi before he made his offer:
| Value | vs. his $476,000 price | |
|---|---|---|
| State's 2026 assessed value | $567,433 | +$91,433 |
| After a light refresh (paint, flooring, cosmetic updates) | about $596,000 | about +$120,000 |
| After a full renovation (after-repair value) | about $615,000 | about +$139,000 |
That gap is the equity Ovi could build by living in the house and fixing it up over time, before subtracting what he spends on the work. That's exactly what he wanted: a primary residence he could improve and grow into. It's also why the price was worth fighting for.
These are my estimates from comparable sales, not an appraisal, and the $50,000 Maryland Mortgage Program loan is repaid when he sells or refinances. But it meant Ovi made his offer knowing what the house could become, not guessing.
The negotiation
We went under contract on June 28, 2026, 12 days after it was listed, with three wins:
- Price: $476,000. That's $24,000 below the $500,000 list price and $59,000 below where the seller started.
- $14,000 seller credit toward Ovi's closing costs, about 2.9% of the price. It covered roughly 69% of his closing costs and prepaid items.
- Sold as-is, closed on time. We settled on July 28, 2026, exactly a month after contract.
On top of that, as a first-time Maryland home buyer, Ovi paid no State transfer tax; Maryland law puts it on the seller at a reduced 0.25% rate (Tax-Property §13-203). And because he'll live in the home, the first $100,000 of the price was exempt from Montgomery County recordation tax. Small things, but they add up.
The $50,000 most first-time buyers don't know about
Ovi used the Maryland Mortgage Program (MMP) with a conventional loan and 10% down. MMP's down payment assistance gave him $50,000 as a 0% interest, no-payment second loan that's repaid in full when he sells or refinances. It's not a grant, and that matters if you plan to refinance soon. But while he lives there, it costs him nothing each month.
The 10% down payment was $47,600, so the $50,000 covered all of it, with $2,400 left over toward closing costs. I explain how the program works, and who qualifies, in Montgomery County's $50,000 down payment help.
How a $5,000 deposit turned into a check back
When we went under contract, Ovi put down a $5,000 earnest money deposit, like every buyer does. At closing, that deposit counts toward what he owes. But between the seller credit and the MMP assistance, he owed less than the deposit, so the title company sent him the difference.
| From the settlement statement | Amount |
|---|---|
| Price | $476,000.00 |
| Closing costs and prepaids (lender, title, taxes, insurance, escrows) | $20,208.10 |
| Total due | $496,208.10 |
| First mortgage (conventional, 90% of price) | −$428,400.00 |
| Maryland Mortgage Program assistance | −$50,000.00 |
| Seller credit | −$14,000.00 |
| Property tax and escrow adjustments | −$1,184.95 |
| Earnest money deposit | −$5,000.00 |
| Due back to Ovi at closing | $2,376.85 |
Ovi's real out-of-pocket cost:
- $5,000 deposit − $2,376.85 back at closing = $2,623.15
- Plus the $550 appraisal he paid before closing = about $3,173 to get the keys to a $476,000 home.
What this means if you're buying in Montgomery County
- Know the after-renovation value before you offer. Ask your agent to run comps for the house as it is and as it could be. That's what tells you whether a fixer-upper is a smart buy.
- "As-is" and "needs work" are negotiating leverage, not just warnings. The right house, at the right moment, can come with both a lower price and closing-cost help.
- Ask about first-time buyer assistance before you decide what you can afford. The Maryland Mortgage Program has income limits, but many Montgomery County buyers qualify and don't know it.
- Run your own numbers. The buyer closing cost calculator shows what you'd need to bring with and without a seller credit, and how to make an offer on a house in Maryland covers how to ask for one.
Frequently asked questions
Can you buy a house in Maryland with almost no money out of pocket?
Sometimes, yes. In this case a first-time buyer combined a seller credit, the Maryland Mortgage Program's down payment assistance, and a below-list price, and brought about $3,200 total. It depends on your income, the loan program, the house, and how motivated the seller is.
What is the Maryland Mortgage Program's $50,000 down payment assistance?
It's down payment and closing cost help for eligible first-time buyers, structured as a 0% interest, no-payment loan that's repaid when you sell or refinance. Income limits and program terms apply and change, so confirm current details with an MMP-approved lender.
Can the seller pay my closing costs in Maryland?
Yes. A seller credit is negotiated in your offer and shows up on the settlement statement. Lenders limit how much a seller can contribute, based on the loan type and your down payment, and the credit can't be more than your actual closing costs.
How do you get money back at closing?
Your earnest money deposit counts toward what you owe at settlement. If credits and assistance cover more than you owe, the title company returns the difference to you. Here, that was $2,376.85.
How do you know if a fixer-upper is a good deal?
Run comparable sales for two values before you offer: what similar homes in the same condition sell for, and what renovated ones sell for. Here, the comps put this house at about $596,000 after a light refresh and about $615,000 fully renovated, against a $476,000 purchase price.
Did the agent have to give up commission to make this work?
No. Everything in this deal came from negotiation with the seller and the Maryland Mortgage Program, not a commission rebate.
Thinking about buying your first home?
I'll look at your numbers, check whether you qualify for assistance, and show you what's realistically possible in Montgomery County before you start touring.
Text me at (301) 357-1170. It's the fastest way to reach me. Or book a free buyer consultation.
Figures are from the final settlement statement and the Bright MLS record for 17313 Dowden Way, shared with the client's permission. Value estimates are Edward's comparable-sales analysis, not an appraisal. Results depend on each property, buyer, and market; this is not a guarantee of similar results or a commitment to lend.
About the Author
Edward Dumitrache
REALTOR®, Pearson Smith Realty
Licensed in MD, DC & VA · 10+ years · 100+ transactions · Montgomery County specialist
MD License 668402 · DC License SP98376910 · VA License 0225228053
Related Reading
Montgomery County's $50,000 Down Payment Help: The 0% Loan Most First-Time Buyers Don't Know About (2026)
Read →
Sell My House Fast in Maryland: How to Get Multiple Cash Offers (Without a "We Buy Houses" Company)
Read →
Bought a Flipped Home in Montgomery County? Why Your Property Tax Jumped (and What You Can Do)
Read →Ready to make a move?
I'm always happy to talk through what's happening locally — no obligation.
Get in Touch